Licensed Medicare Agents Near You in Southern California
Medicare guidance you can trust — year after year. Compare Medicare Advantage, Medigap and Part D plans with a local licensed agent, at no cost to you.
Licensed in 46 states
Offices across Southern California
Se habla español
No cost to you
Speak With a Licensed Agent
Your agent helps you enroll, compare Medicare options, and choose the coverage that best fits your needs.
Answer a few quick questions so a licensed insurance agent can understand your needs and review Medicare plan options available in your area. It takes about 2 minutes.
This is a solicitation for insurance. You may be contacted by a licensed insurance agent.
Your way
Explore Your Medicare Options — Your Way
Choose how you’d like to learn about Medicare. Whether you prefer speaking with a licensed insurance agent, reviewing plans online, or scheduling a call, we’re here to help you understand your options.
Speak With a Licensed Agent
Get guidance from a licensed Boomers Insurance agent over the phone.
Medicare plan changes are subject to eligibility and qualifying enrollment periods. Not all consumers qualify to enroll in or change plans at any time of the year. A licensed insurance agent can help determine eligibility based on the consumer’s situation.
A licensed agent walks you through your options, in English or Spanish.
How it works
Three steps to a plan you understand
There is no cost for an agent’s help, and no pressure to decide on the first call.
1
Tell us about you
Your doctors, your prescriptions, your budget and how you prefer to get care. By phone, online or at an office.
2
We compare the plans in your county
A licensed agent reviews the Medicare Advantage, Medigap and Part D plans offered where you live and explains the differences in plain language.
3
Enroll, and keep your agent
Your agent helps you enroll and stays your contact year after year: new cards, plan changes, questions about a bill.
Medicare vs Medicare Advantage vs Medigap: what’s the difference?
Original Medicare is Part A (hospital) and Part B (medical) from the federal government. A Medicare Advantage plan (Part C) gives you your Part A and Part B coverage through a private company that contracts with Medicare, usually with drug coverage included. A Medigap policy (Medicare Supplement) works alongside Original Medicare and helps pay the costs Original Medicare leaves to you.
Medicare, in four parts (plus Medigap)
A
Part A
Hospital Insurance
Inpatient hospital stays, skilled nursing facility care, hospice and some home health care.
B
Part B
Medical Insurance
Doctor visits, outpatient care, preventive services and durable medical equipment.
C
Part C
Medicare Advantage
Part A and Part B through a private plan that contracts with Medicare; most plans include drug coverage.
D
Part D
Drug coverage
Prescription drug coverage from a private plan, added to Original Medicare.
+
Medigap
Medicare Supplement Insurance
Sold by private companies; helps pay some of the costs Original Medicare leaves to you, such as deductibles and coinsurance.
Two ways to put your coverage together
Option 1
Original Medicare, with add-ons
Keep Part A and Part B from the federal government and add what you need.
APart ABPart BDPart D plan+Medigap policy
Any provider in the US that accepts Medicare
A separate Part D plan for prescriptions
A Medigap policy helps pay deductibles and coinsurance
or
Option 2
Medicare Advantage (Part C)
One plan from a private company that contracts with Medicare.
Included in one plan
APart ABPart BDUsually Part D
Part A, Part B and usually Part D in one plan
A provider network, with referrals in most HMOs
A yearly out-of-pocket maximum; many plans add dental, vision or hearing benefits
Side by side
Original Medicare
Who runs it
The federal government
Doctor choice
Any provider in the US that accepts Medicare
Drug coverage
Not included; add a Part D plan
Extra benefits
Routine dental, vision and hearing generally not covered
Out-of-pocket costs
Deductibles and coinsurance, with no yearly limit on what you pay
Medicare Advantage (Part C)
Who runs it
Private companies that contract with Medicare
Doctor choice
HMOs generally need in-network providers and referrals; PPOs allow out-of-network care at a higher cost
Drug coverage
Usually included
Extra benefits
Many plans include some dental, vision and hearing benefits; they vary by plan
Out-of-pocket costs
Copays or coinsurance up to the plan’s yearly out-of-pocket maximum
Medigap (Medicare Supplement)
Who runs it
Private insurers; it works with Original Medicare
Doctor choice
Same as Original Medicare
Drug coverage
Not included; add a Part D plan
Extra benefits
Not included; stand-alone dental or vision insurance can be bought
Out-of-pocket costs
The policy helps pay deductibles and coinsurance, depending on the plan
How Original Medicare, Medicare Advantage and Medigap compare
Feature
Original Medicare
Medicare Advantage (Part C)
Medigap (Medicare Supplement)
Who runs it
The federal government
Private companies that contract with Medicare
Private insurers; it works with Original Medicare
Doctor choice
Any provider in the US that accepts Medicare
HMOs generally need in-network providers and referrals; PPOs allow out-of-network care at a higher cost
Same as Original Medicare
Drug coverage
Not included; add a Part D plan
Usually included
Not included; add a Part D plan
Extra benefits
Routine dental, vision and hearing generally not covered
Many plans include some dental, vision and hearing benefits; they vary by plan
Not included; stand-alone dental or vision insurance can be bought
Out-of-pocket costs
Deductibles and coinsurance, with no yearly limit on what you pay
Copays or coinsurance up to the plan’s yearly out-of-pocket maximum
The policy helps pay deductibles and coinsurance, depending on the plan
The table is a general guide. Costs and benefits differ from plan to plan, so compare the actual plans offered where you live.
Medigap vs Medicare Advantage: which one fits you?
A Medigap policy keeps Original Medicare and any doctor in the United States who accepts it, helps pay Original Medicare’s deductibles and coinsurance, and pairs with a separate Part D plan. A Medicare Advantage plan puts hospital, medical and usually drug coverage in one plan with a provider network, a yearly out-of-pocket maximum and often some dental, vision or hearing benefits. You cannot have both at the same time. Which one fits you depends on your doctors, your prescriptions and how you prefer to pay; a licensed agent can compare the plans offered in your county with you.
Medicare has set windows for joining and changing plans. The dates are the same every year; outside them you need a Special Enrollment Period.
JJan
FFeb
MMar
AApr
MMay
JJun
JJul
AAug
SSep
OOct
NNov
DDec
Annual Enrollment
MA Open Enrollment
General Enrollment
Annual Enrollment Period
October 15 – December 7 · Everyone with Medicare
Join, switch or drop a Medicare Advantage or Part D plan. Changes start January 1.
Medicare Advantage Open Enrollment Period
January 1 – March 31 · People already in a Medicare Advantage Plan
One change: switch to another Medicare Advantage Plan, or go back to Original Medicare and add a Part D plan.
General Enrollment Period
January 1 – March 31 · People who did not sign up when first eligible
Sign up for Part A and/or Part B. Coverage starts the month after you sign up; a late enrollment penalty may apply.
Turning 65? Your 7-month window
Initial Enrollment Period
-3
-2
-1
65
+1
+2
+3
Starts 3 months before the month you turn 65 and ends 3 months after it. Sign up before your birthday month and coverage usually starts the month you turn 65. If you have coverage from a job, you may be able to delay Part B without a penalty.
Plain-language guides to Medicare’s enrollment dates and rules, checked against official Medicare and California sources. Annual Enrollment runs October 15 – December 7, 2026.
How much Medicare costs depends on which parts you have. In 2026 the standard Part B premium is $202.90 a month and the Part A hospital deductible is $1,736. CMS has not yet announced the 2027 Part A and Part B amounts, while the 2027 Part D cap and a few other figures are confirmed. Here is your Me
Does Medicare pay for hearing aids? Not under Original Medicare: it doesn’t cover hearing aids or the exams to fit them, so you pay the full cost. Part B does cover diagnostic hearing and balance exams. Many Medicare Advantage plans add a hearing benefit, and over-the-counter hearing aids, Medi-Cal
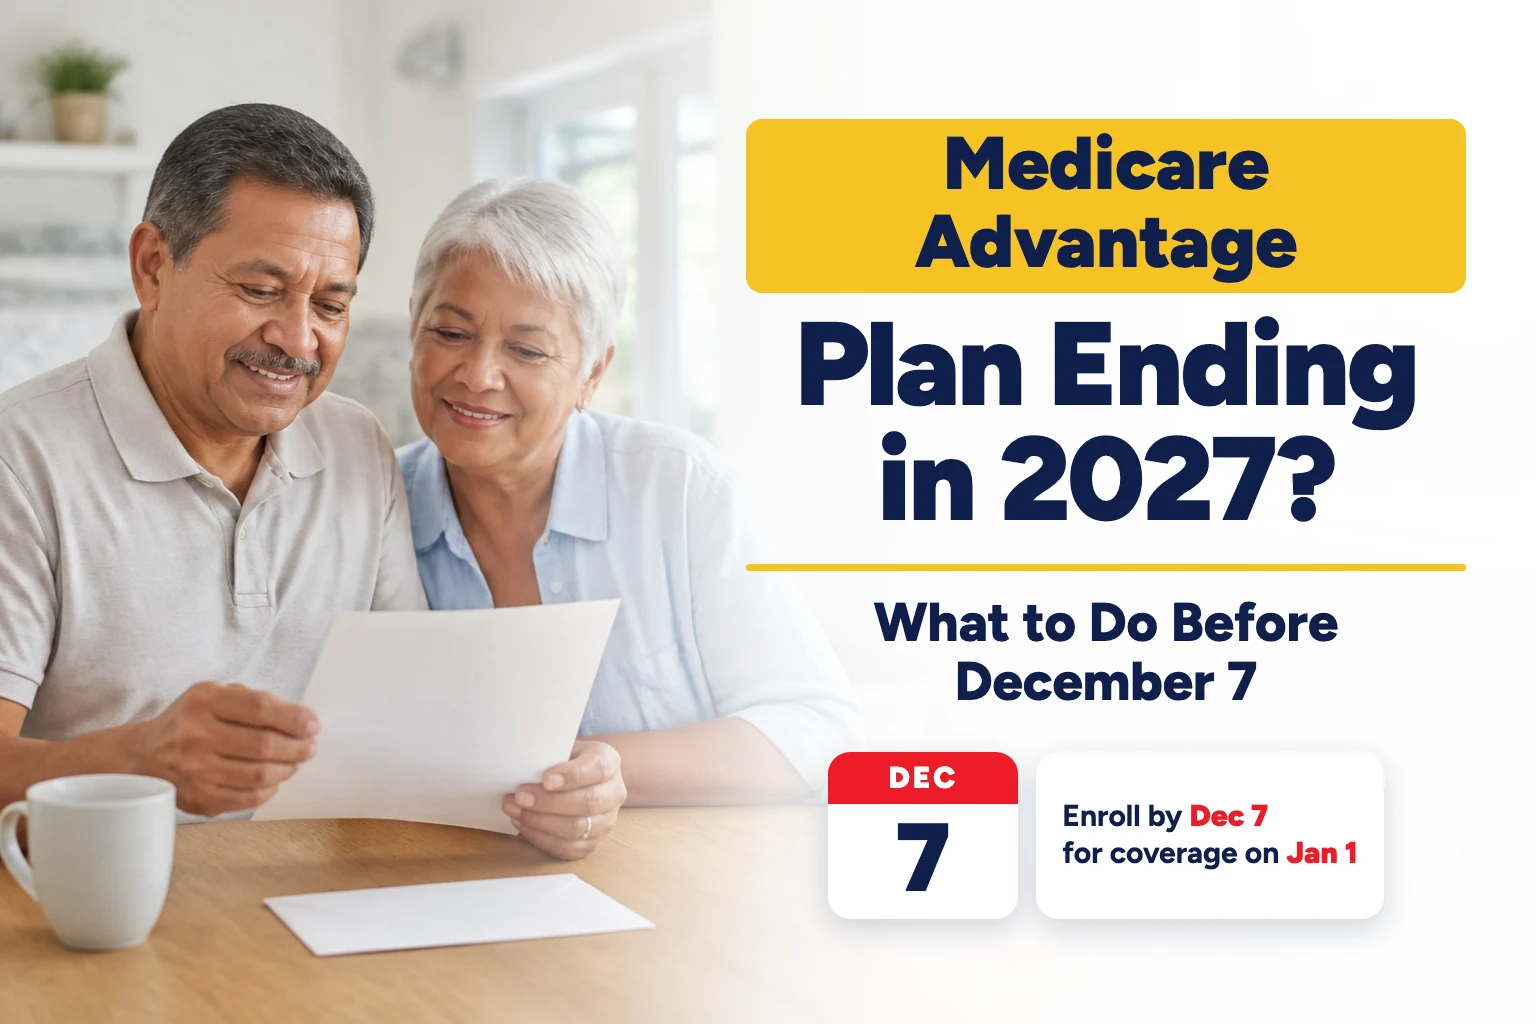
Got a letter about your Medicare Advantage plan ending on December 31, 2026? You need to choose new coverage. You can pick a plan during the Annual Enrollment Period through December 7, 2026, or in a Special Enrollment Period that runs December 8, 2026 to February 28, 2027. If you do nothing, you go
Medicare and VA benefits are separate programs, and generally they can’t pay for the same care, so you choose which one to use each time. Here’s how veterans can decide on Part A and Part B, how VA drug coverage affects Part D, what TRICARE For Life requires, and what to do before 65.
Boomers Insurance Services is a Medicare agency based in Downey, with licensed agents across Los Angeles, Orange, Riverside and San Bernardino counties, and agents who also serve San Diego and the Bay Area. Meet a licensed Medicare agent at one of our offices, by phone, by video, or at your home. Many of our agents speak Spanish, and we hold Medicare 101 workshops in person every month.
10offices
in California, Nevada and Texas
109licensed agents
listed on our site
5languages
spoken by our agents
16counties
with a local agent
Pick your county to see the licensed Medicare agents near you.
Short answers from licensed agents. For the full list, see the Medicare FAQs, or call 1-800-815-1943 (TTY 711).
How do I find a licensed Medicare agent near me?
Use Find an Agent to search by city, county or language, or browse the Medicare agents in your county. Every Boomers agent is licensed in California and appointed with the plans they offer.
You can also walk into one of our offices, including the Downey headquarters, or call 1-800-815-1943 (TTY 711), Monday to Friday, 9 AM to 5 PM Pacific.
What does Medicare cover?
Original Medicare has two parts. Part A covers hospital stays, skilled nursing care and hospice. Part B covers doctor visits, outpatient care, preventive services and medical equipment.
Prescription drugs come through a Part D plan or a Medicare Advantage plan that includes drug coverage. Routine dental, vision and hearing are generally not covered by Original Medicare; some Medicare Advantage plans include them.
What is the difference between Medicare Advantage and Medigap?
A Medicare Advantage plan (Part C) replaces how you receive your Part A and Part B benefits: a private company that contracts with Medicare delivers them, usually with drug coverage and a provider network.
A Medigap policy (Medicare Supplement) works alongside Original Medicare and helps pay the deductibles and coinsurance Original Medicare leaves to you. You keep any provider in the United States that accepts Medicare. You cannot have both at the same time.
Does it cost anything to work with a Boomers agent?
No. There is no cost to you for a licensed agent’s help; agents are paid by the plan you enroll in. An agent can only enroll you in the plans they are appointed with.
We do not offer every plan available in your area. Any information we provide is limited to those plans we do offer in your area. Please contact Medicare.gov or 1-800-MEDICARE to get information on all your options.
Can I get help with Medicare in Spanish?
Yes. Many of our agents speak Spanish, and some speak Vietnamese or Chinese. Filter Find an Agent by language, or ask for a Spanish-speaking agent when you call.
Our Spanish-language Medicare guide, Información en español, explains enrollment dates and rules for California.