Medicare Supplement Plan G: What It Covers and What It Doesn’t
Medicare Supplement Plan G is a standardized Medigap plan. It pays your share of Original Medicare’s covered costs, including Part B excess charges, except the Part B deductible ($283 in 2026).
Medicare Supplement Plan G is one of the standardized Medigap plans sold by private insurance companies. It works with Original Medicare (Part A and Part B). After Medicare pays its share of a covered service, Plan G pays your share, with one exception: the Part B deductible. In 2026, that deductible is $283.
Plan G is often compared with Plan F, which people new to Medicare can no longer buy, and with Plan N. Below we explain what Plan G pays, what it doesn’t, and how its high-deductible version works. We also cover when you can buy it without health questions, including California’s rules.
What does Medicare Supplement Plan G cover?
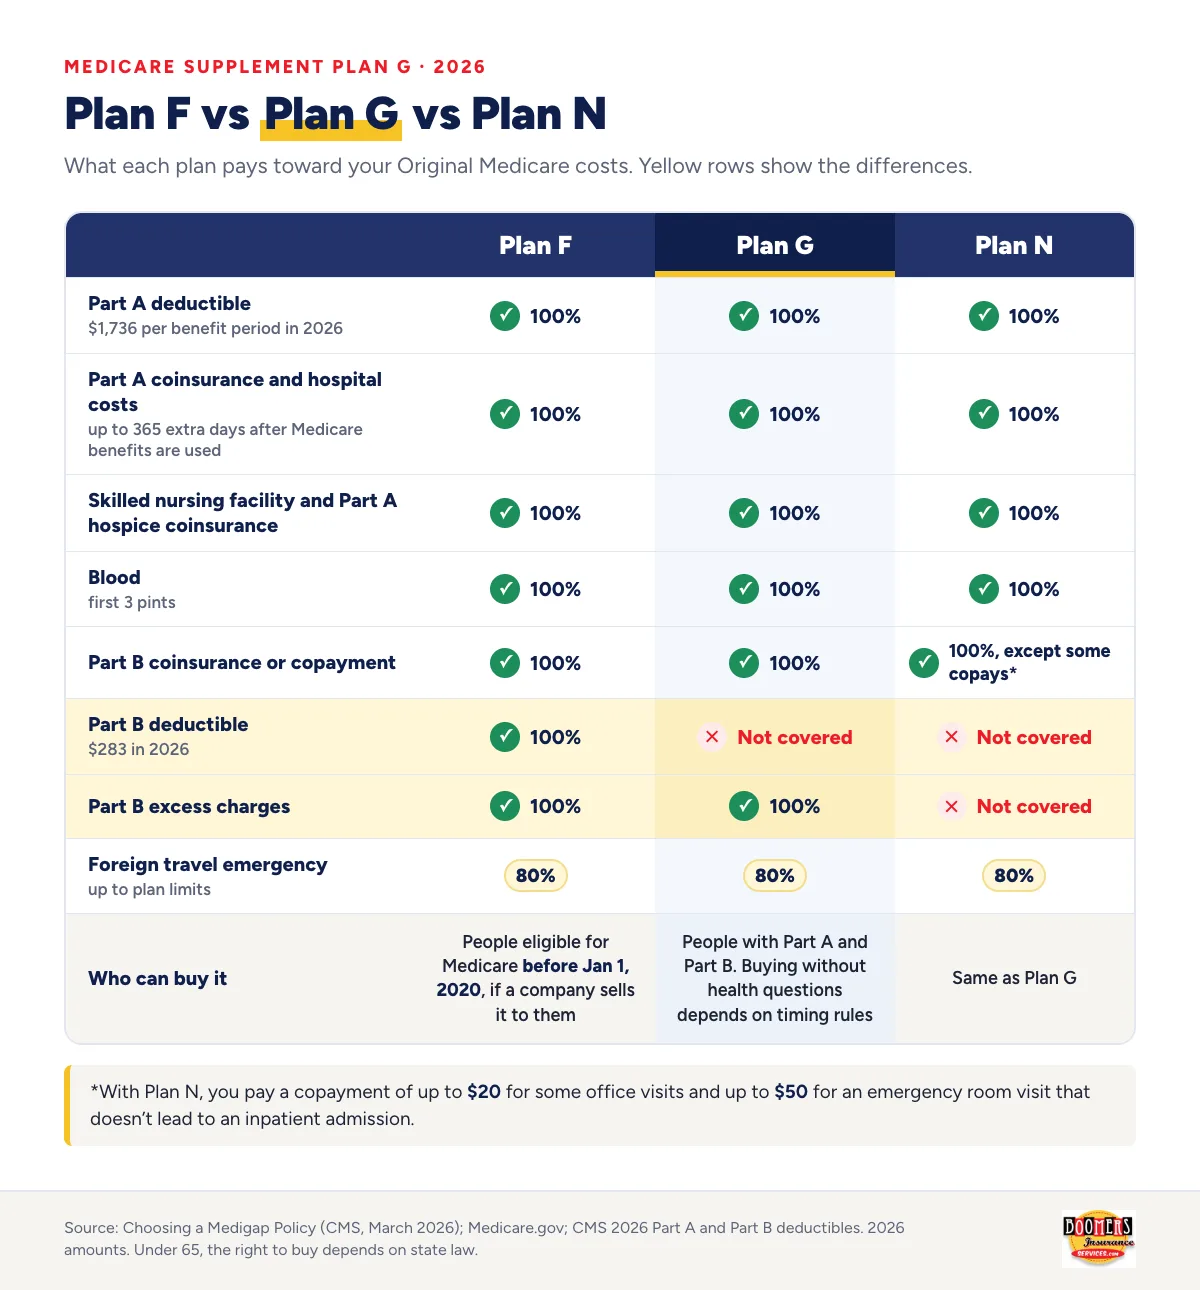
Medigap plans with the same letter offer the same basic benefits, whatever company sells them. So Plan G coverage is set by law in most states. Using Medicare’s 2026 chart, here is what Plan G pays compared with Plans F and N:
| Cost in Original Medicare | Plan F | Plan G | Plan N |
|---|---|---|---|
| Part A coinsurance and hospital costs, up to 365 extra days after Medicare benefits are used | 100% | 100% | 100% |
| Part A deductible ($1,736 per benefit period in 2026) | 100% | 100% | 100% |
| Skilled nursing facility coinsurance | 100% | 100% | 100% |
| Part A hospice coinsurance or copayment | 100% | 100% | 100% |
| Blood (first 3 pints) | 100% | 100% | 100% |
| Part B coinsurance or copayment | 100% | 100% | 100%, except some copays* |
| Part B deductible ($283 in 2026) | 100% | Not covered | Not covered |
| Part B excess charges | 100% | 100% | Not covered |
| Foreign travel emergency, up to plan limits | 80% | 80% | 80% |
| Who can buy it | People eligible for Medicare before Jan 1, 2020, if a company sells it to them | People with Part A and Part B; the right to buy without health questions depends on the timing rules below (under 65, on state law) | Same as Plan G |
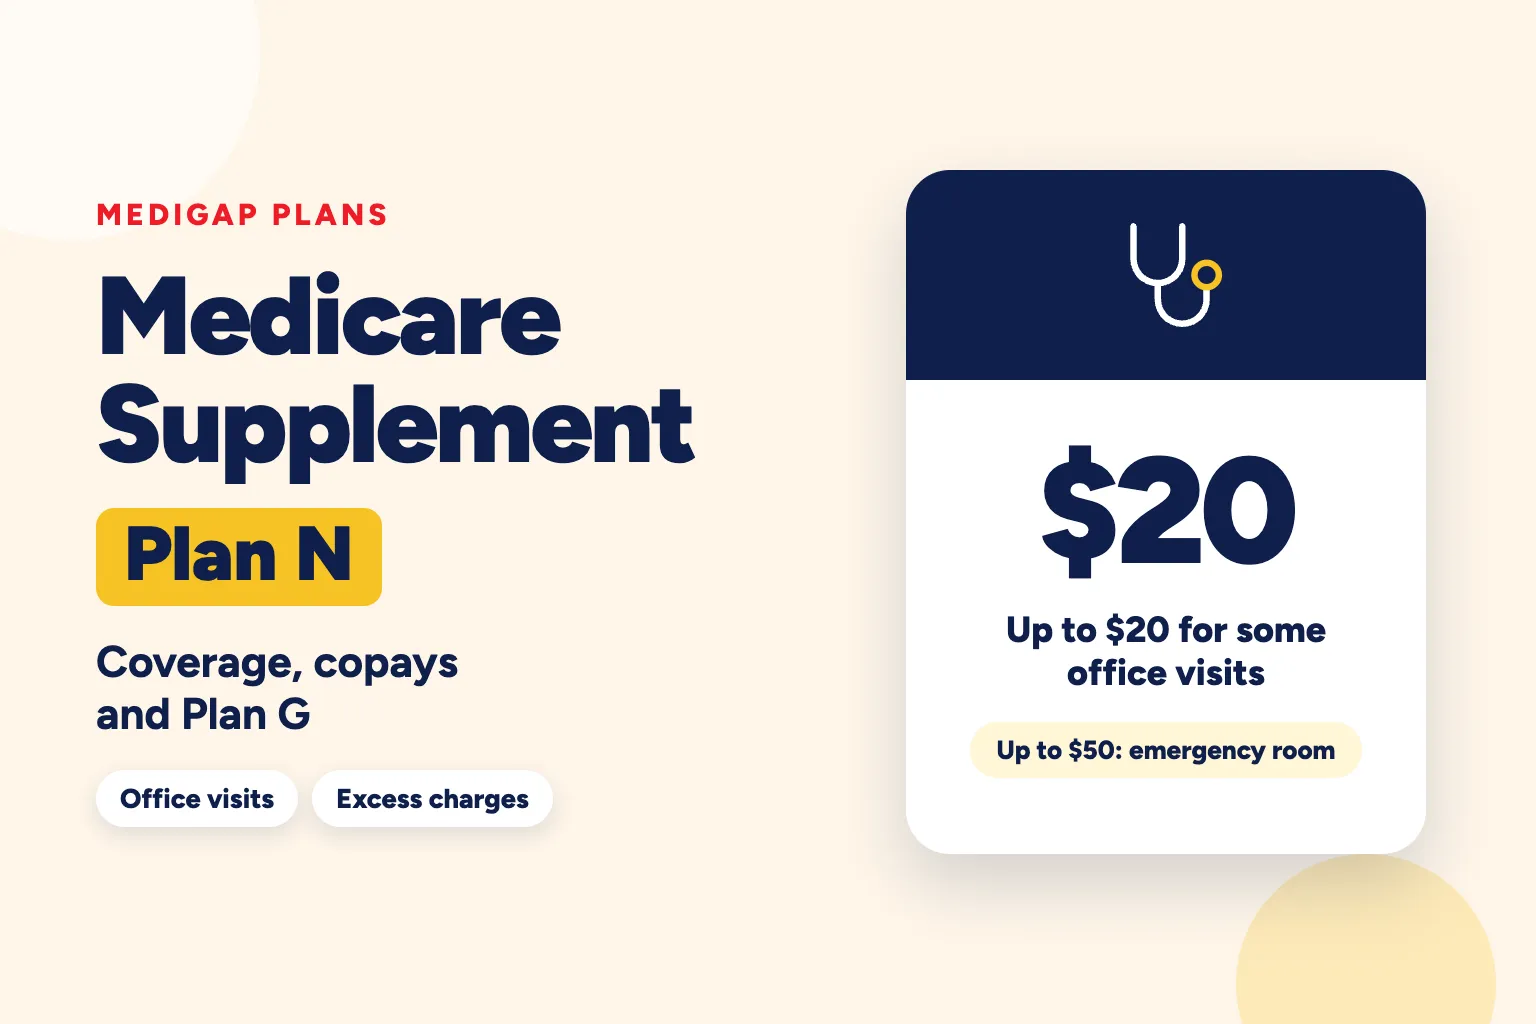
*With Plan N, you pay a copayment of up to $20 for some office visits and up to $50 for an emergency room visit that doesn’t lead to an inpatient admission.
In practice, once you have paid the Part B deductible for the year, Plan G generally pays the rest of your share for services Original Medicare covers.
What doesn’t Medicare Plan G cover?
Plan G only pays toward care that Original Medicare covers, plus emergency care abroad. It doesn’t pay:
- The Part B deductible. You pay it yourself each year. CMS had not announced the 2027 amount when we checked on November 4, 2026.
- Prescription drugs. Medigap policies sold after 2005 don’t include drug coverage, so if you want drug coverage, you can join a separate Part D plan.
- Routine dental, vision, hearing aids or glasses. Medigap generally doesn’t cover these.
- Long-term care, like non-skilled care in a nursing home, or private-duty nursing.
- Part of foreign travel emergency care: the first $250 each year, 20% of the rest, and anything over the $50,000 lifetime limit. It covers only emergencies that begin in the first 60 days of a trip.
You also keep paying your Part B premium to Medicare. Plan G has its own monthly premium on top of that.
What are Part B excess charges?
Doctors who accept assignment take the amount Medicare allows as full payment, and you pay only the Medicare deductible and coinsurance. Some doctors accept Medicare but don’t accept assignment for every service. Medicare.gov says they can charge more, and in many cases the charge can’t be more than 15% above the amount Medicare allows. That extra amount is the Part B excess charge.
Among the standard letters sold today, only Plans F and G pay excess charges. If your doctors accept assignment, excess charges may never come up. You can ask a doctor’s office whether it accepts assignment before you get care.
Doctors who have opted out of Medicare are different. Medicare won’t pay for their services, except in emergencies, and you may be asked to sign a private contract. Ask before you get care.
Plan F vs Plan G: what’s the difference?
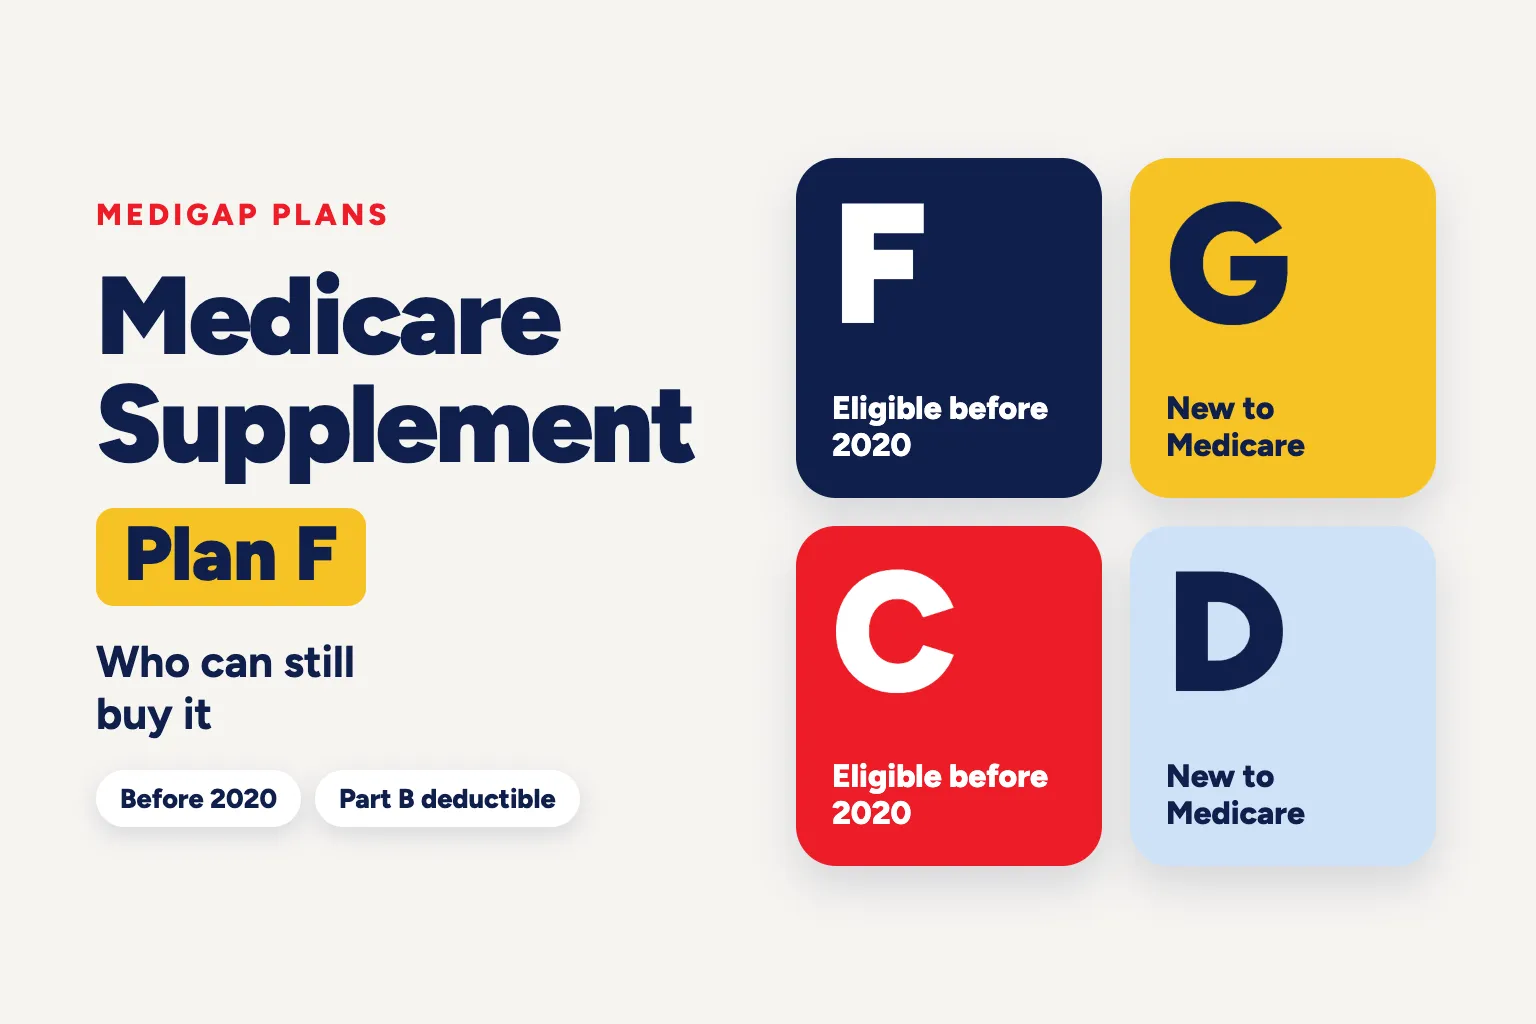
Plan F and Plan G give the same benefits, except one: Plan F also pays the Part B deductible.
Since January 1, 2020, Medigap plans sold to people new to Medicare can’t pay the Part B deductible. So if you became eligible for Medicare on or after that date, you can’t buy Plan F (or Plan C). Medicare’s booklet says people new to Medicare can buy Plan G instead. If you were eligible before 2020 but hadn’t enrolled, you may still be able to buy Plan F. For who can still buy it, read our Medicare Supplement Plan F guide.
If you already have Plan F, you can generally keep it. Moving from Plan F to Plan G outside a protected time may mean answering health questions. California’s birthday rule, explained below, may let you move to a plan with equal or lesser benefits.
Plan G vs Plan N: how do they compare?
Plans G and N pay the same share of Part A costs, including the Part A deductible and hospital, skilled nursing and hospice coinsurance. Neither pays the Part B deductible. The differences are:
- Copayments. With Plan N, you may pay up to $20 at some office visits and up to $50 for an emergency room visit that doesn’t lead to an admission. Plan G has no such copayments.
- Excess charges. Plan G pays them. Plan N doesn’t.
Premiums for each letter vary by company, age and area, so compare actual quotes for both letters. If you see doctors who don’t accept assignment, Plan G’s coverage of excess charges may matter more to you. For the copayments in detail, read our Medicare Supplement Plan N guide.
What is high-deductible Plan G?
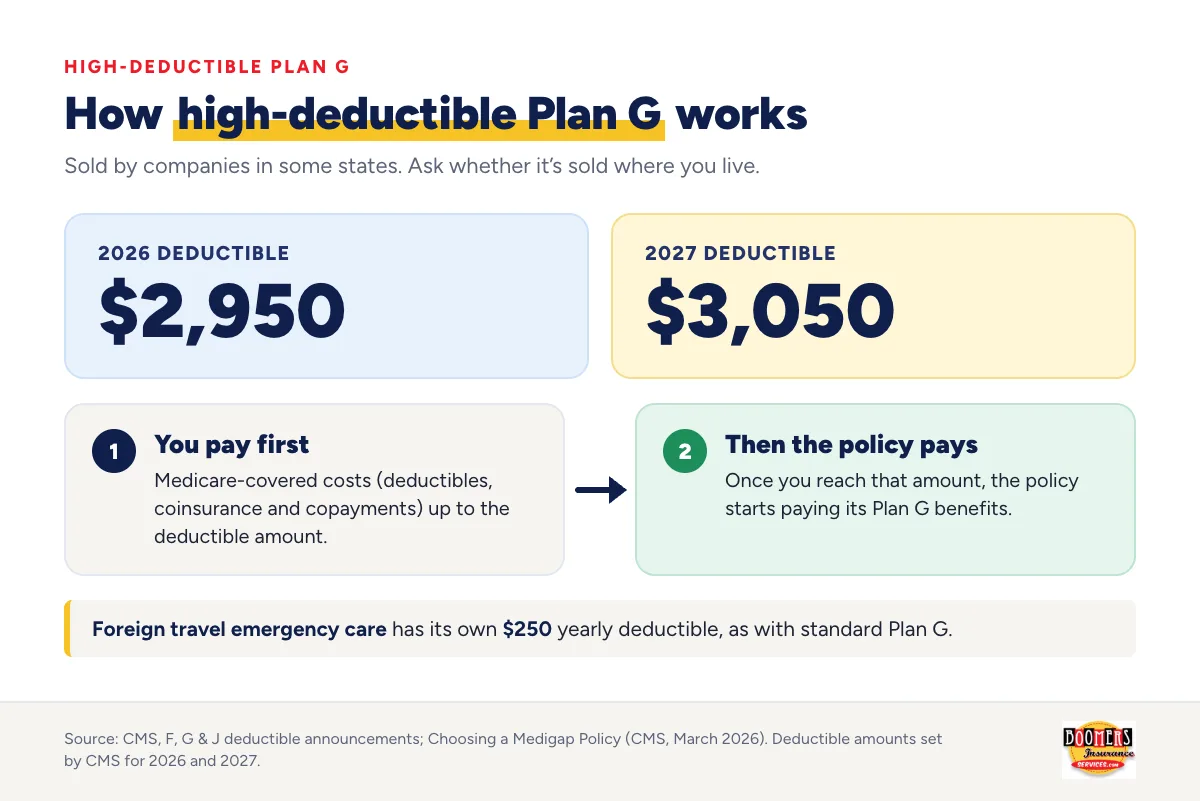
In some states, companies also sell a high-deductible version of Plan G. You pay Medicare-covered costs (deductibles, coinsurance and copayments) up to a set amount before the policy pays anything. CMS set that amount at:
- $2,950 for 2026
- $3,050 for 2027
Once you reach that amount, the policy starts paying its Plan G benefits. Foreign travel emergency care has its own $250 yearly deductible, as with standard Plan G. With this version, you take on more of your costs before the policy pays. Ask whether it’s sold where you live.
When can you buy Medicare Supplement Plan G?
Your Medigap open enrollment period
Your Medigap open enrollment period is a one-time, 6-month window. It starts the first month you have Part B and are 65 or older. During it, a company can’t refuse to sell you any Medigap policy it offers, including Plan G. It also can’t charge you more for health problems. It may make you wait up to 6 months to cover a pre-existing condition, unless you had at least 6 months of creditable coverage with no break over 63 days.
If you delay Part B because you have group coverage from your or your spouse’s current job, your window starts when you sign up. See Medicare and employer insurance for that timing.
Medigap protections and trial rights
Outside that window, a company can generally use your health to decide. But federal law gives you the right to buy Plan G (and Plans A, B and D) from a company that sells it in your state in certain situations. Examples are when your Medicare Advantage plan stops giving care in your area, or your employer coverage that pays after Medicare ends. In some cases, trial rights also apply if you leave Medicare Advantage within your first year. Depending on the situation, you can apply as early as 60 days before your coverage ends, and generally no later than 63 days after it ends.
If your Medicare Advantage plan is ending, our guide on what to do when a Medicare Advantage plan is ending explains the dates.
California’s birthday rule
If you already have a Medigap policy in California, you have an annual window of at least 60 days beginning on your birthday. In it, you can switch to another Medigap plan with equal or lesser benefits; the company can’t turn you down or charge you more because of your health. Which plans count as equal or lesser depends on the policy you have now. HICAP (1-800-434-0222) or the California Department of Insurance hotline (1-800-927-4357) can help you check.
What affects the Plan G premium?
We don’t quote premiums, because they vary by company, age, ZIP code and pricing method. Medicare’s booklet says the premium is the only difference between Plan G policies from different companies. The way a company prices the policy matters too:
- Community-rated: the premium is generally the same whatever your age.
- Issue-age-rated: based on your age when you buy.
- Attained-age-rated: based on your current age, so it rises as you get older.
Any of them may still go up because of inflation and other factors. Compare Plan G from one company with Plan G from another, and ask how each prices it. Our Medicare costs guide covers the Part B premium and deductible you pay alongside it.
Next steps
- Find your Part B start date. Your 6-month Medigap window starts then, if you’re 65 or older.
- List your doctors and ask whether they accept assignment.
- Compare Plan G with Plan N, and with high-deductible Plan G if it’s sold in your area.
- Choose a Part D plan for prescriptions, since Plan G doesn’t include drug coverage.
- Turning 65 soon? Our Turning 65 checklist puts the steps in order.
Talk with a licensed Boomers agent
A licensed Boomers agent can go over the Medicare plans we represent in your area and check them against your doctors and prescriptions. We can also compare Plan G with the other Medigap letters and with Medicare Advantage.
Find a licensed agent near you · See upcoming Medicare events
Or call 1-800-815-1943 (TTY 711), Monday – Friday, 9 AM – 5 PM Pacific.
Frequently asked questions
Does Plan G cover the Part B deductible?
No. With Plan G, you pay the Part B deductible yourself: $283 in 2026. After that, Plan G pays your share of covered Part B costs, including excess charges. Check Medicare.gov for the latest amounts.
Can I switch from Plan F to Plan G?
You may be able to. Outside your open enrollment period, a company can generally ask health questions and decide whether to sell you Plan G. In California, if you already have a Medigap policy, the birthday rule lets you move to a plan with equal or lesser benefits; the company can’t turn you down or charge you more because of your health. If you switch, you get 30 days to review the new policy, and you pay both premiums for the month you have both.
Can I use Plan G with any doctor?
Plan G works with any doctor or hospital in the U.S. that accepts Medicare. The exception is a Medicare SELECT version, which uses a hospital network and sometimes a doctor network. Medicare SELECT is sold only in some states.
Does Medicare Supplement Plan G cover prescriptions?
No. Medigap policies sold after 2005 don’t include drug coverage. You can join a separate Medicare drug plan (Part D), which usually has its own premium. Our Part D out-of-pocket cap guide explains the yearly limits.
Sources
- Choosing a Medigap Policy, March 2026 (Medicare.gov)
- Compare Medigap plan benefits (Medicare.gov)
- Does your provider accept Medicare as full payment? (Medicare.gov)
- Medicare & You 2027 handbook (Medicare.gov)
- F, G & J deductible announcements (CMS.gov)
- 2026 Medicare Parts A & B premiums and deductibles (CMS.gov)
- California Insurance Code § 10192.11, Medigap open enrollment and the birthday rule (California Legislative Information)
- Informing Seniors and the Senior Insurance Bill of Rights, Form 805 (California Department of Insurance, July 2025)
- Medicare counseling: HICAP (California Department of Aging)
Talk with a licensed Boomers agent
A licensed agent can go over the Medicare plans we represent in your area, check them against your doctors and prescriptions, and answer your questions. There is no cost to you and no obligation to enroll.
Monday – Friday, 9 AM – 5 PM PT