Medicare Supplement Plan N: What It Covers and Its Copays
Medicare Supplement Plan N is a standardized Medigap plan. It pays most of your share of Original Medicare's covered costs.
Medicare Supplement Plan N is one of the standardized Medigap plans sold by private insurance companies. It works with Original Medicare (Part A and Part B). After Medicare pays its share of a covered service, Plan N pays most of your share. You pay a few costs yourself: the Part B deductible, some copayments and any Part B excess charges.
This guide uses Medicare's own chart and the 2026 and 2027 amounts from the Centers for Medicare & Medicaid Services (CMS). It explains what Plan N pays, what you pay, how it compares with Plan G, and when you can buy it.
What does Medicare Supplement Plan N cover?
Plan N pays 100% of most Medicare cost-sharing items on Medicare's Medigap benefits chart. Medigap plans with the same letter offer the same basic benefits, whatever company sells them. So a Plan N Medicare Supplement policy has the same benefits from one company to the next in most states.
| Cost in Original Medicare | Plan N pays |
|---|---|
| Part A coinsurance and hospital costs, up to 365 extra days after Medicare benefits are used | 100% |
| Part A deductible ($1,736 per benefit period in 2026; $1,776 in 2027) | 100% |
| Skilled nursing facility coinsurance | 100% |
| Part A hospice coinsurance or copayment | 100% |
| Blood (first 3 pints) | 100% |
| Part B coinsurance or copayment | 100%, except the copayments below |
| Part B deductible ($283 in 2026; $292 in 2027) | Not covered |
| Part B excess charges | Not covered |
| Foreign travel emergency, up to plan limits | 80% |
Foreign travel emergency care has limits. The plan pays 80% of certain emergency care outside the U.S. after you meet a $250 deductible for the year, up to a $50,000 lifetime limit. The care must begin in the first 60 days of your trip.
What are the Plan N copays?
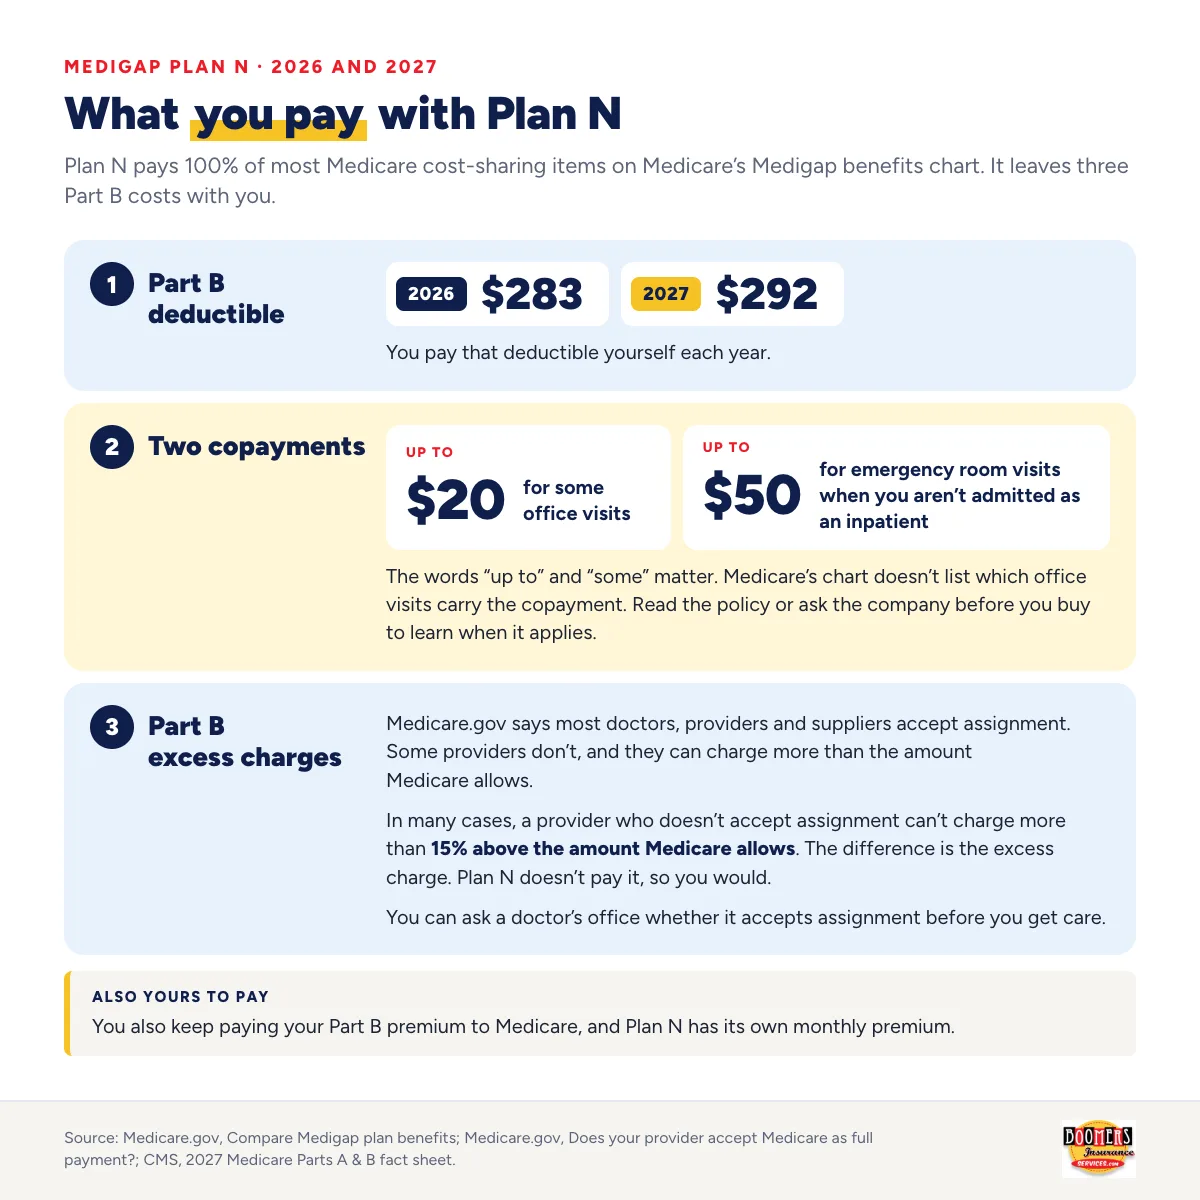
Plan N pays 100% of the Part B coinsurance, with two exceptions that Medicare.gov describes. You pay:
- A copayment of up to $20 for some office visits.
- A copayment of up to $50 for emergency room visits when you aren't admitted as an inpatient.
The words "up to" and "some" matter. Medicare's chart doesn't list which office visits carry the copayment. Read the policy or ask the company before you buy to learn when it applies.
These copayments are separate from the Part B deductible. You pay that deductible yourself each year, whichever Medigap letter you have, unless you have Plan C or Plan F, the two letters on Medicare's chart that pay it.
What doesn't Medicare Plan N cover?
Plan N leaves three Part B costs with you, and, apart from foreign travel emergency care, it doesn't pay for care that Original Medicare doesn't cover. Here is the list:
- The Part B deductible: $283 in 2026 and $292 in 2027.
- The copayments above: up to $20 for some office visits and up to $50 for emergency room visits when you aren't admitted as an inpatient.
- Part B excess charges, explained in the next section.
- Prescription drugs. Medigap policies sold after 2005 don't include drug coverage. You can join a separate Medicare drug plan (Part D).
- Dental or vision care, hearing aids or glasses. Medigap generally doesn't cover these.
- Long-term care, like non-skilled care in a nursing home, or private-duty nursing.
You also keep paying your Part B premium to Medicare, and Plan N has its own monthly premium.
What are Part B excess charges?
Doctors who accept assignment take the amount Medicare allows as full payment. You pay only the Medicare deductible and coinsurance. Medicare.gov says most doctors, providers and suppliers accept assignment.
Some providers don't. Medicare.gov says they can charge more than the amount Medicare allows. In many cases, a provider who doesn't accept assignment can't charge more than 15% above the amount Medicare allows. Medicare calls this the limiting charge. It doesn't apply to some supplies and medical equipment. The difference is the excess charge. Plan N doesn't pay it, so you would. You can ask a doctor's office whether it accepts assignment before you get care.
Plan G vs Plan N: how do they compare?
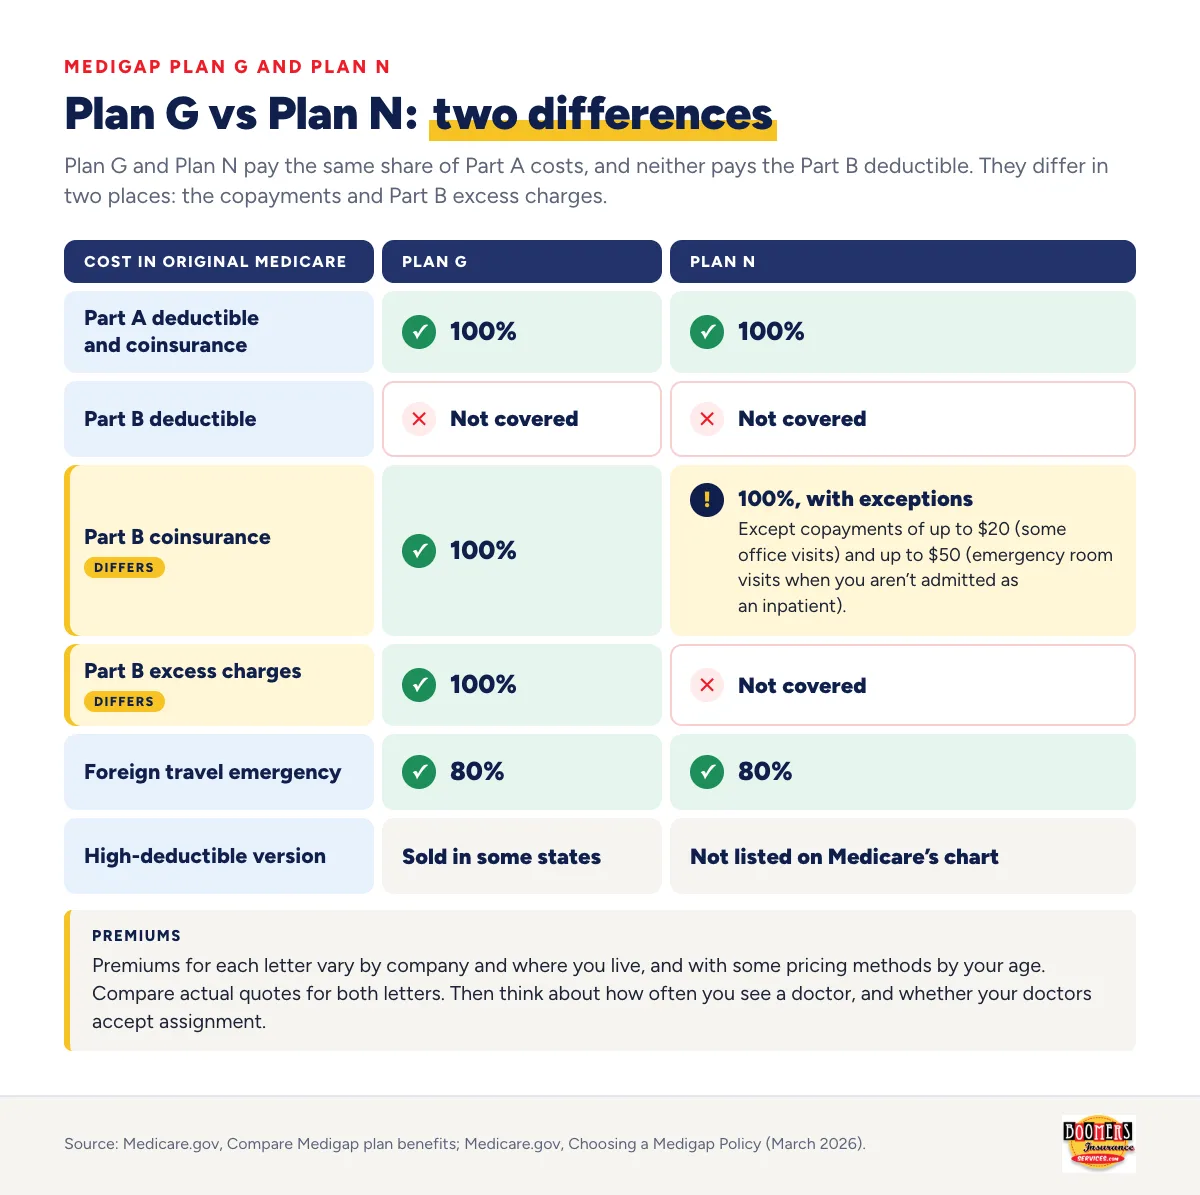
Plan G and Plan N pay the same share of Part A costs, and neither pays the Part B deductible. They differ in two places: the copayments and Part B excess charges.
| Plan G | Plan N | |
|---|---|---|
| Part A deductible and coinsurance | 100% | 100% |
| Part B deductible | Not covered | Not covered |
| Part B coinsurance | 100% | 100%, except copayments of up to $20 (some office visits) and up to $50 (emergency room visits when you aren't admitted as an inpatient) |
| Part B excess charges | 100% | Not covered |
| Foreign travel emergency | 80% | 80% |
| High-deductible version | Sold in some states | Not listed on Medicare's chart |
Premiums for each letter vary by company and where you live, and with some pricing methods by your age, so we don't quote them. Compare actual quotes for both letters. Then think about how often you see a doctor, and whether your doctors accept assignment.
Our Medicare Supplement Plan G guide covers that plan in full. Plan F is the letter that also pays the Part B deductible, but people new to Medicare since 2020 can't buy it. See our Medicare Supplement Plan F guide.
Who can buy Plan N, and when?
Generally, you need Original Medicare, both Part A and Part B, to buy a Medigap policy. Plan N is open to people new to Medicare. When you apply affects whether a company can ask about your health.
Your Medigap open enrollment period
This is a one-time, 6-month window. It starts the first month you have Part B and are 65 or older. During it, a company can't refuse to sell you any Medigap policy it offers, and it can't charge you more because of health problems. After this window, Medicare.gov says you may not be able to buy a Medigap policy, or it may cost more.
A few situations give you the right to buy certain Medigap policies outside that window. In most of these situations the plans named are A, B, C, D, F or G, not Plan N. Our Medicare vs Medigap guide explains these protected times.
California's birthday rule
If you already have a Medigap policy in California, you have an annual window of at least 60 days beginning on your birthday. In it, you can switch to another Medigap plan with equal or lesser benefits, without medical screening or a new waiting period.
Which plans count as equal or lesser depends on the policy you have now. To check your own case, call HICAP, California's Health Insurance Counseling & Advocacy Program, at 1-800-434-0222. You can also call the California Department of Insurance at 1-800-927-4357.
What affects the Plan N premium?
Each company sets its own premium, and Medicare.gov says price is the only difference between plans with the same letter from different companies. Three pricing methods are common:
- Community-rated: the premium is generally the same whatever your age.
- Issue-age-rated: based on your age when you buy.
- Attained-age-rated: based on your current age, so it rises as you get older.
Any of them may still go up because of inflation and other factors. Ask each company how it prices Plan N. Our Medicare Supplement plans overview compares the letters side by side.
Next steps
Start with your dates and your doctors, then compare the letters. These steps put it in order.
- Find your Part B start date. Your 6-month Medigap window starts then, if you're 65 or older.
- Ask your doctors whether they accept assignment. Plan N doesn't pay excess charges.
- Compare Plan N with Plan G using actual quotes for each.
- Choose a Part D plan for prescriptions, since Plan N doesn't include drug coverage.
- Turning 65 soon? Our Turning 65 checklist lists each step.
Talk with a licensed Boomers agent
A licensed Boomers agent can go over the Medicare plans we represent in your area and check them against your doctors and prescriptions.
Find a licensed agent near you · See upcoming Medicare events
Or call 1-800-815-1943 (TTY 711), Monday – Friday, 9 AM – 5 PM Pacific.
Frequently asked questions
Is there a Medicare Part N?
No. Medicare has Part A, Part B, Part C and Part D. People who search for "Medicare Part N" usually mean Plan N, which is a Medigap plan letter, not a part of Medicare. A private insurance company sells it, and it works only with Original Medicare.
Does Plan N cover the Part B deductible?
No. You pay the Part B deductible yourself: $283 in 2026 and $292 in 2027. After that, Plan N pays the Part B coinsurance, except its copayments for some office visits and for emergency room visits when you aren't admitted as an inpatient.
Do I pay the $50 copayment if the emergency room admits me?
Medicare.gov says the copayment of up to $50 applies to emergency room visits when you aren't admitted as an inpatient. Ask the company if you aren't sure how your policy handles a visit.
Can I use Medicare Supplement Plan N with any doctor?
Plan N works with Original Medicare, which lets you use any doctor or hospital in the U.S. that takes Medicare. If a provider doesn't accept assignment, you may owe an excess charge, which Plan N doesn't pay. A Medicare SELECT version of a Medigap policy may require you to use certain providers.
Sources
- Compare Medigap plan benefits (Medicare.gov)
- Choosing a Medigap Policy, March 2026 (Medicare.gov)
- Learn what Medigap covers (Medicare.gov)
- Get Medigap basics (Medicare.gov)
- Get ready to buy (Medicare.gov)
- Does your provider accept Medicare as full payment? (Medicare.gov)
- Medicare coverage outside the United States (Medicare.gov)
- 2027 Medicare Parts A & B premiums and deductibles (CMS.gov, November 17, 2026)
- Medicare Supplement Insurance "Medigap" (California Department of Insurance)
- Informing seniors guide, updated July 2025 (California Department of Insurance)
- Medicare counseling: HICAP (California Department of Aging)
Talk with a licensed Boomers agent
A licensed agent can go over the Medicare plans we represent in your area, check them against your doctors and prescriptions, and answer your questions. There is no cost to you and no obligation to enroll.
Monday – Friday, 9 AM – 5 PM PT