Medicare vs Medigap: How Original Medicare and Medigap Fit Together
Medicare vs Medigap isn’t a choice between two programs. Original Medicare (Part A and Part B) is the government’s health insurance. Medigap is a private policy that helps pay what Original Medicare leaves to you, like deductibles and coinsurance.
Medicare vs Medigap isn’t a choice between two programs. Original Medicare (Part A and Part B) is the federal health plan. Medigap, also called Medicare Supplement Insurance, is a policy you buy from a private company. It helps pay costs Original Medicare leaves to you, such as deductibles, coinsurance and copayments. You need Part A and Part B first; Medigap adds to them and doesn’t replace them.
Below, we explain what each one pays in 2026 and when you can buy a policy with no health questions. We also cover California’s own Medigap rules. Torn between Medigap and a Medicare Advantage plan? Read our Medicare Advantage vs Medigap in California comparison.
Original Medicare vs Medigap at a glance
| Original Medicare (Part A and Part B) | Medigap (Medicare Supplement Insurance) | |
|---|---|---|
| Who offers it | The federal government | Private insurance companies, under federal and state law |
| What it pays for | Hospital (Part A) and medical (Part B) services | Part of your share of the costs for services Original Medicare covers |
| Monthly premium | Part B: $202.90 standard in 2026. Most people get Part A without a premium | A separate premium to the insurance company, on top of Part B |
| Doctors | Any doctor or hospital in the U.S. that accepts Medicare | The same (Medicare SELECT policies use a hospital network) |
| Drug coverage | No. You can join a separate Part D plan | No, for policies sold after 2005 |
| Who it covers | You | One person. Spouses buy their own policies |
What does Original Medicare pay, and what does it leave to you?
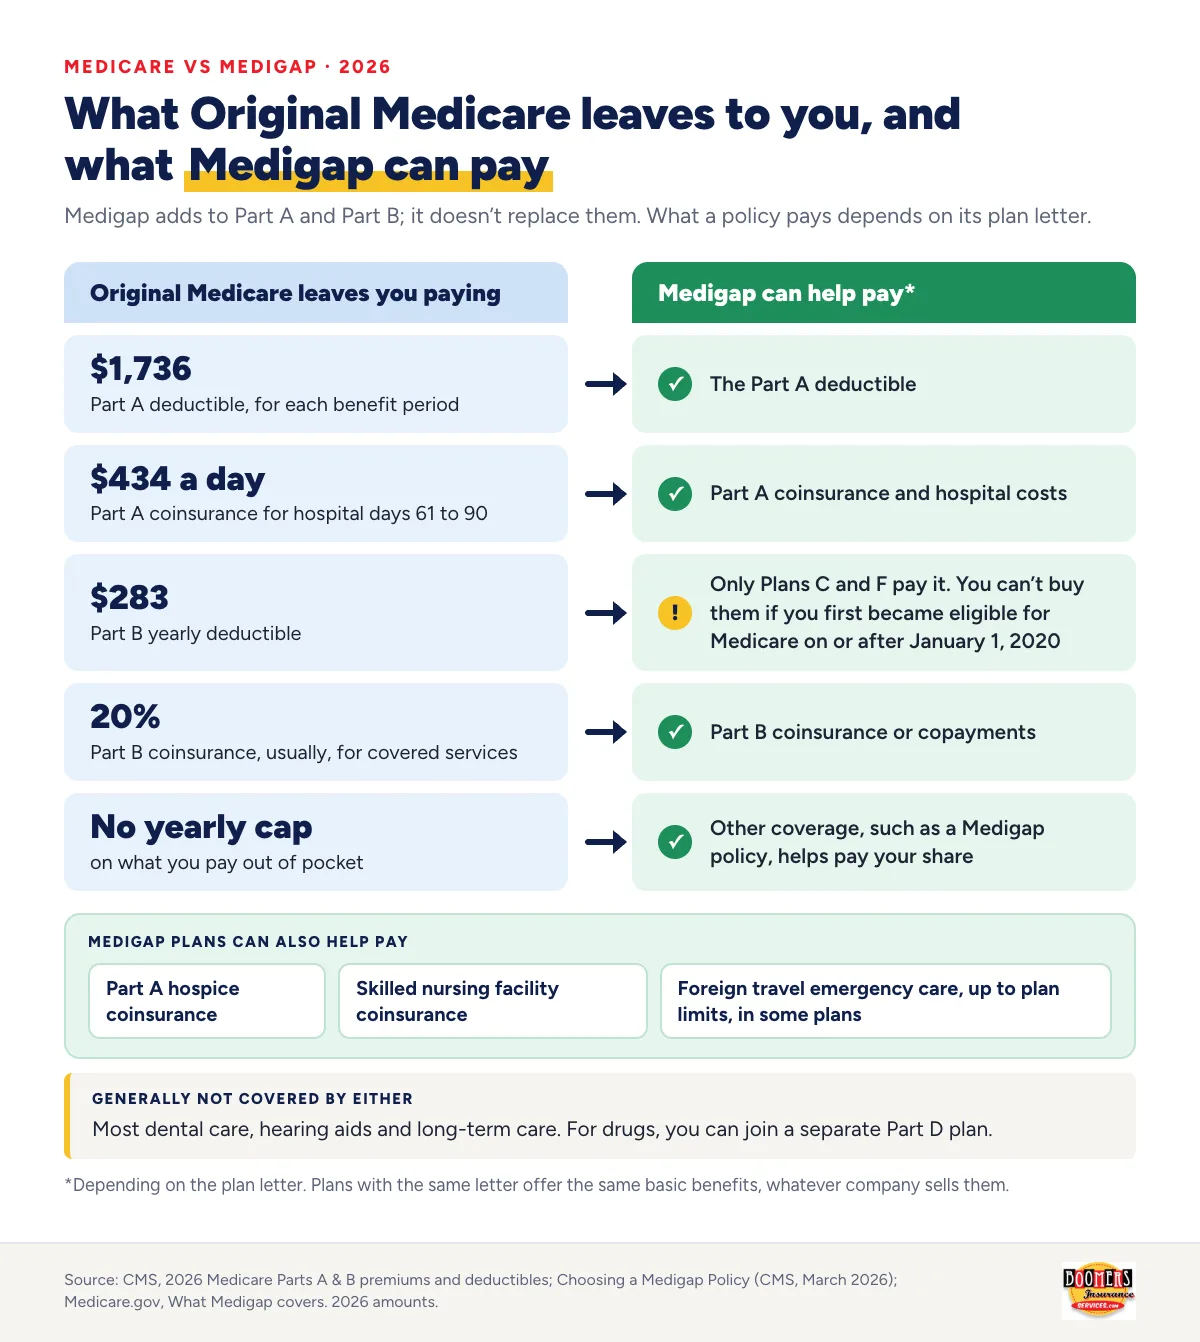
Original Medicare pays a large share of covered care, but not all of it. In 2026, CMS set these amounts:
- Part A (hospital): a $1,736 deductible for each benefit period, then $434 a day for days 61 to 90 of a hospital stay.
- Part B (medical): a $283 yearly deductible, then usually 20% coinsurance for covered services.
- No yearly cap: Original Medicare has no limit on what you pay out of pocket in a year unless you have other coverage, such as a Medigap policy.
Original Medicare also doesn’t cover most dental care, hearing aids or long-term care. Medigap generally doesn’t cover those either. Our articles on dental insurance for seniors, hearing aid coverage and long-term care explain the other ways to pay. The full list of 2026 amounts, and the 2027 ones announced so far, is in our Medicare costs guide.
What is Medigap?
Medigap policies are sold by private companies. Each one must be clearly labeled “Medicare Supplement Insurance.” In most states, the plans are set by law and named by letters: A to D, F, G and K to N. Plans with the same letter offer the same basic benefits, whatever company sells them. Medicare’s Medigap booklet says the premium is the only difference between policies with the same letter from different companies.
What Medigap plans can help pay, depending on the letter:
- Part A coinsurance and hospital costs
- The Part A deductible and Part A hospice coinsurance
- Part B coinsurance or copayments
- Skilled nursing facility coinsurance
- Foreign travel emergency care, up to plan limits, in some plans
Two rules about plan letters matter. If you first became eligible for Medicare on or after January 1, 2020, you can’t buy Plan C or F. Those two pay the Part B deductible. Plan D gives the same benefits as Plan C, and Plan G the same as Plan F, except that deductible. Also, a Medigap policy only works with Original Medicare. It’s illegal for anyone to sell you one while you’re in a Medicare Advantage plan, unless you’re switching back to Original Medicare.
Medicare vs Medigap: what do you pay?
With Medigap, you pay two premiums: your Part B premium to Medicare, and the Medigap premium to the company. Medicare.gov says prices can vary between companies for the same coverage. They may also go up as you get older. So compare the same letter across companies.
Plans F and G also come in a high-deductible version in some states. CMS set that deductible at $2,950 for 2026 and $3,050 for 2027. You pay up to that amount in Medicare-covered costs before the policy starts to pay.
When can you buy a Medigap policy?
Your Medigap open enrollment period
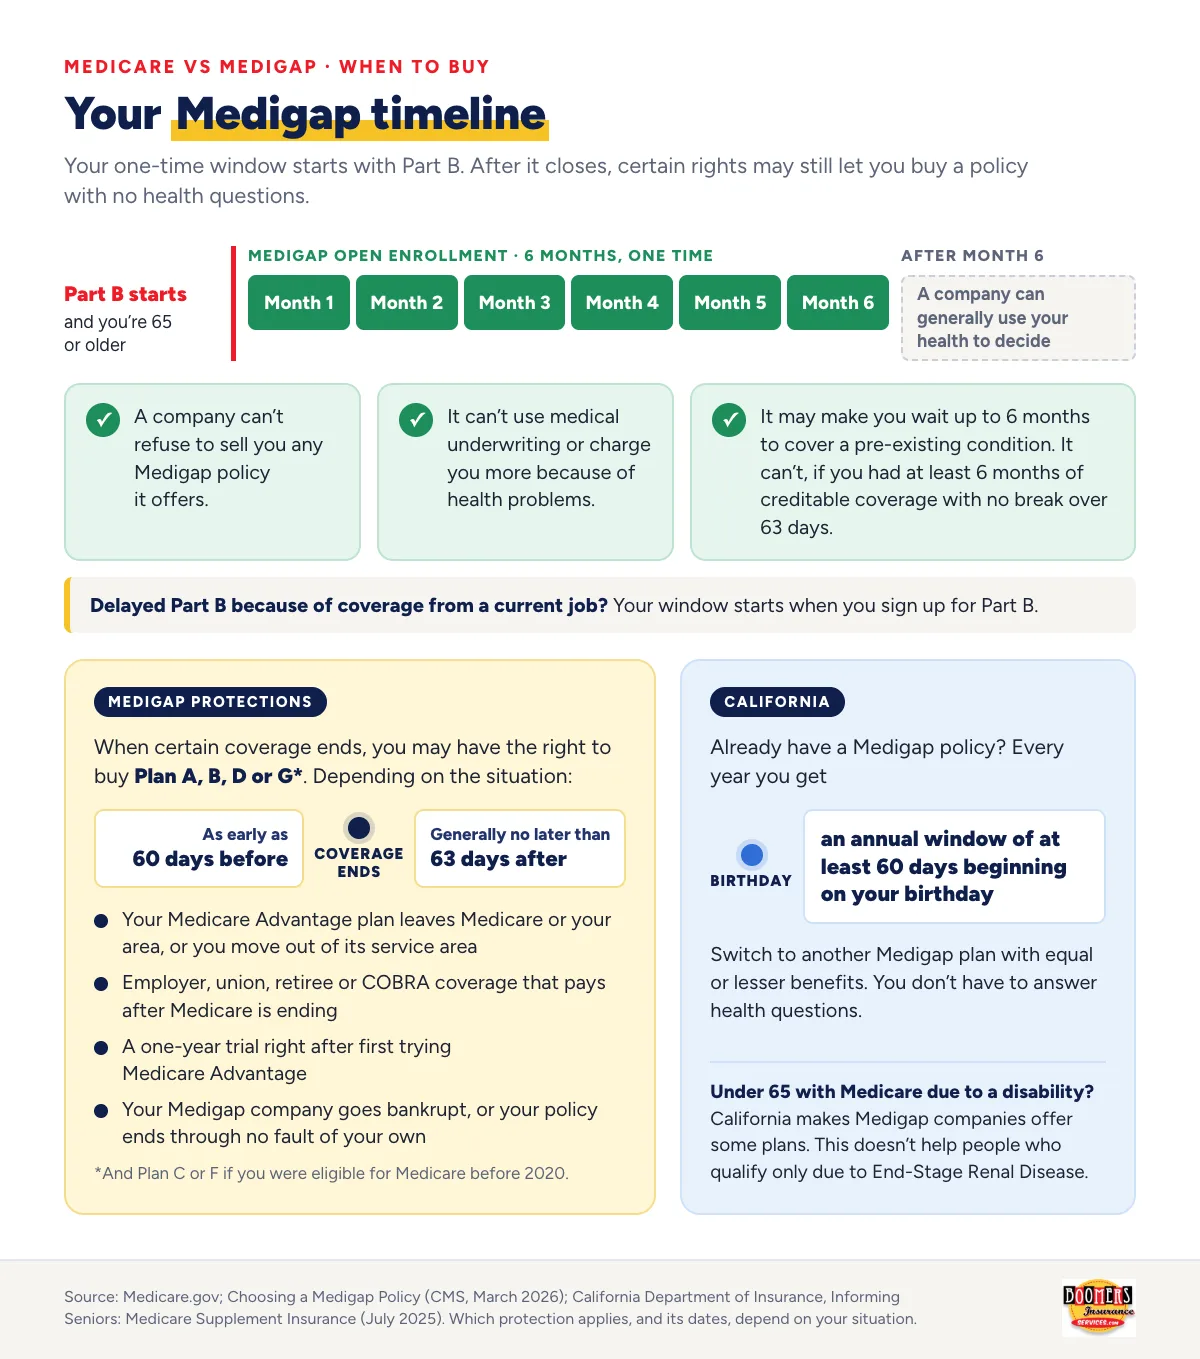
Your Medigap open enrollment period is a one-time, 6-month window. It starts the first month you have Part B and are 65 or older. During it, according to Medicare.gov:
- An insurance company can’t refuse to sell you any Medigap policy it offers.
- It can’t use medical underwriting or charge you more because of health problems.
- It may make you wait up to 6 months to cover a pre-existing condition. It can’t, if you had at least 6 months of creditable coverage with no break over 63 days.
If you delay Part B because you have coverage from a current job, your window starts when you sign up for Part B. Our article on Medicare and employer insurance explains that timing.
Medigap protections after open enrollment
After the window closes, a company can generally use your health to decide whether to sell you a policy. But in some cases, federal law gives you the right to buy certain plans with no health questions. Medicare calls these Medigap protections. The most common ones are:
- Your Medicare Advantage plan leaves Medicare or stops giving care in your area, or you move out of its service area, and you switch to Original Medicare.
- Your employer, union, retiree or COBRA coverage that pays after Medicare is ending.
- You’re within a one-year trial right after first trying a Medicare Advantage plan.
- Your Medigap company goes bankrupt, or your policy ends through no fault of your own.
In most of these situations you can buy Plan A, B, D or G, and Plan C or F if you were eligible for Medicare before 2020. Timing matters: depending on the situation, you can apply as early as 60 days before your coverage ends, and generally no later than 63 days after it ends. Keep the letters that show your coverage ended. If your plan is ending this year, see what to do when a Medicare Advantage plan is ending.
What extra Medigap rules does California have?
California adds a right for people who already have a Medigap policy: an annual window of at least 60 days starting on your birthday. In that time, you can switch to another Medigap plan with equal or lesser benefits. You don’t have to answer health questions. The California Department of Insurance explains the rule.
The state also makes Medigap companies offer some plans to people under 65 who get Medicare due to a disability. That rule doesn’t help people who qualify only due to kidney failure (End-Stage Renal Disease). Our article on Medicare under 65 explains the details.
Need one-on-one help? Call HICAP at 1-800-434-0222. It’s the state’s Medicare counseling program. For a question about a policy or a company, the state’s insurance hotline is 1-800-927-4357.
Do I need a Medicare Supplement?
Nobody is required to buy one. It depends on your health, your budget and your other coverage. These questions can help you decide:
- Could you pay a large bill if you needed a long hospital stay or many tests? Original Medicare alone has no yearly cap.
- Do you have retiree coverage, Medi-Cal or another plan that already helps pay what Medicare doesn’t?
- Do you want to keep any doctor in the U.S. who accepts Medicare, or are you open to a plan with a network?
- Are you inside your 6-month open enrollment window, when your health can’t be used against you?
Many people turning 65 compare Medigap with Medicare Advantage at the same time. Our Turning 65 checklist walks through the order of steps.
Next steps
- Note when your Part B starts. Your 6-month Medigap open enrollment period starts then, if you’re 65 or older.
- List your doctors, prescriptions and travel plans. They help you weigh Medigap against Medicare Advantage.
- Compare the same plan letter across insurance companies; only the premium differs.
- Plan for drug coverage. Medigap doesn’t include it, so look at a Part D plan too.
- Already have Medigap in California? Mark your birthday window each year.
Talk with a licensed Boomers agent
A licensed Boomers agent can go over the Medicare plans we represent in your area and check them against your doctors and prescriptions. We can also explain how your Medigap open enrollment period lines up with your Part B start date.
Find a licensed agent near you · See upcoming Medicare events
Or call 1-800-815-1943 (TTY 711), Monday – Friday, 9 AM – 5 PM Pacific.
Frequently asked questions
Is Medigap the same as Medicare Supplement Insurance?
Yes. They are two names for the same kind of policy. Private companies sell it, and it works only with Original Medicare.
What is Medigap open enrollment, and can I get it later?
It’s a one-time, 6-month period that starts the first month you have Part B and are 65 or older. It doesn’t repeat. After it ends, you may still buy a policy, but the company can usually ask health questions unless you have a Medigap protection.
Can I have Medigap and Medicare Advantage at the same time?
No. A Medigap policy can’t pay Medicare Advantage costs. It’s also illegal to sell you one while you’re in Medicare Advantage, unless you’re going back to Original Medicare. If you drop Medigap to try Medicare Advantage for the first time, a trial right may let you go back within a year.
Does Medigap cover prescription drugs?
No. Policies sold after 2005 don’t cover drugs. Most people with Medigap also join a separate drug plan (Part D).
Can I change Medigap plans in California?
Yes, in some cases without medical questions. If you already have a Medigap policy, California gives you an annual window of at least 60 days starting on your birthday to switch to a plan with equal or lesser benefits. Outside that window, the new company may ask about your health.
Sources
- Medicare & You 2027 handbook (Medicare.gov)
- Choosing a Medigap Policy, March 2026 (Medicare.gov)
- What Medigap covers (Medicare.gov)
- 2026 Medicare Parts A & B premiums and deductibles (CMS.gov)
- F, G & J deductible announcements (CMS.gov)
- Informing Seniors: Medicare Supplement Insurance, Form 805 (California Department of Insurance, July 2025)
- Medicare counseling: HICAP (California Department of Aging)
Talk with a licensed Boomers agent
A licensed agent can go over the Medicare plans we represent in your area, check them against your doctors and prescriptions, and answer your questions. There is no cost to you and no obligation to enroll.
Monday – Friday, 9 AM – 5 PM PT