IRMAA Brackets 2027 (and 2026): Medicare Premiums by Income
The IRMAA brackets 2027 are not out yet. CMS usually publishes them in the fall with the new Part B premium, and they will be based on your 2025 tax return. Until then, the 2026 brackets from CMS apply: no surcharge with a modified adjusted gross income of $109,000 or less (single) or $218,000 or le
If you have a higher income, Medicare charges you more for Part B and Part D. The extra amount is called IRMAA, the income-related monthly adjustment amount. People search for the IRMAA brackets 2027 to plan ahead, but CMS has not published them yet. We checked on November 4, 2026.
Below are the official 2026 brackets, how the 2027 numbers will be set, and what to do if your income has dropped. We will update this page when CMS publishes the 2027 figures.
Are the IRMAA brackets 2027 out yet?
Not yet. CMS announces the next year's Part B premium, deductible and IRMAA amounts together, usually in the fall: the 2025 figures came out on November 8, 2024, and the 2026 figures on November 14, 2025.
Until CMS publishes, there is no Medicare premiums 2027 by income chart from CMS. Some websites show an estimated Medicare premium for 2027, based on forecasts. Those are projections, not CMS figures, so we don't list them here.
What we can tell you now is how the IRMAA brackets 2027 will work. The rules come from federal law and Social Security.
How the 2027 IRMAA brackets will be decided
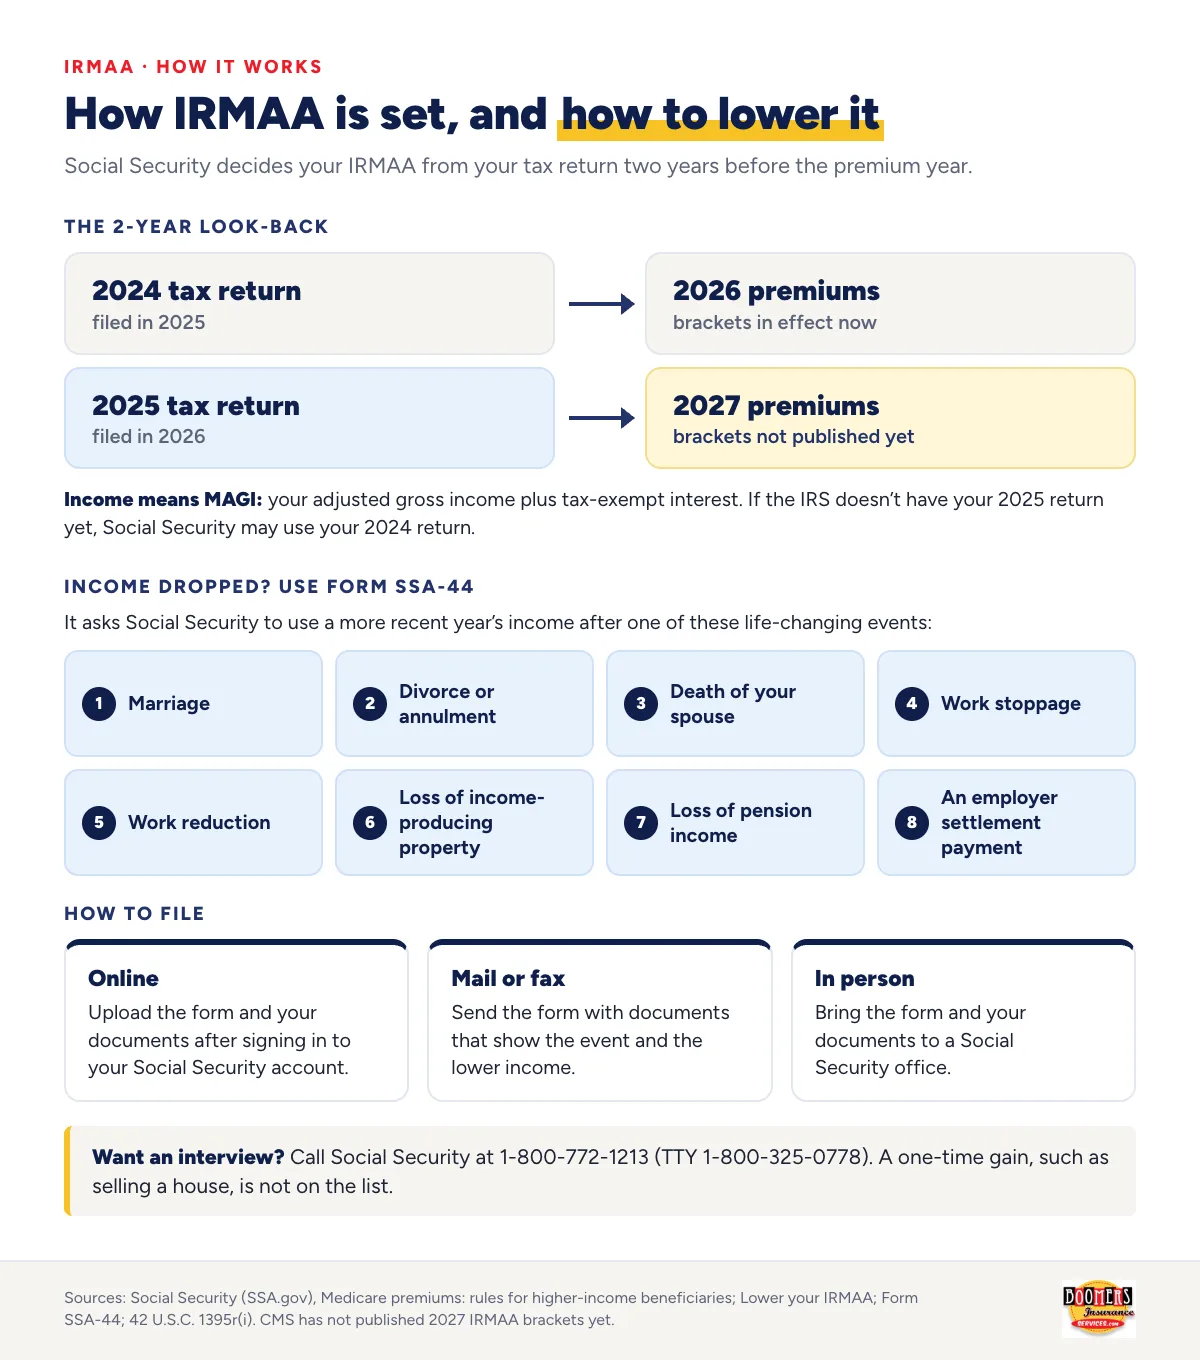
- Your 2025 tax return counts. The law uses your tax return from two years before the premium year. For 2027, that is generally your 2025 return, filed in 2026. If the IRS doesn't have it yet, Social Security may use your 2024 return.
- Income means MAGI. Social Security uses your modified adjusted gross income: your adjusted gross income plus tax-exempt interest.
- The thresholds move with inflation. The law raises the income thresholds each year with the consumer price index, rounded to the nearest $1,000. The top threshold ($500,000 for a single filer) is not adjusted until the years after 2027.
- The surcharges follow the Part B cost. Social Security says higher-income people pay 35%, 50%, 65%, 80% or 85% of the total cost of Part B, instead of the standard 25%. So the 2027 dollar amounts depend on the 2027 premium.
2026 IRMAA brackets and premiums
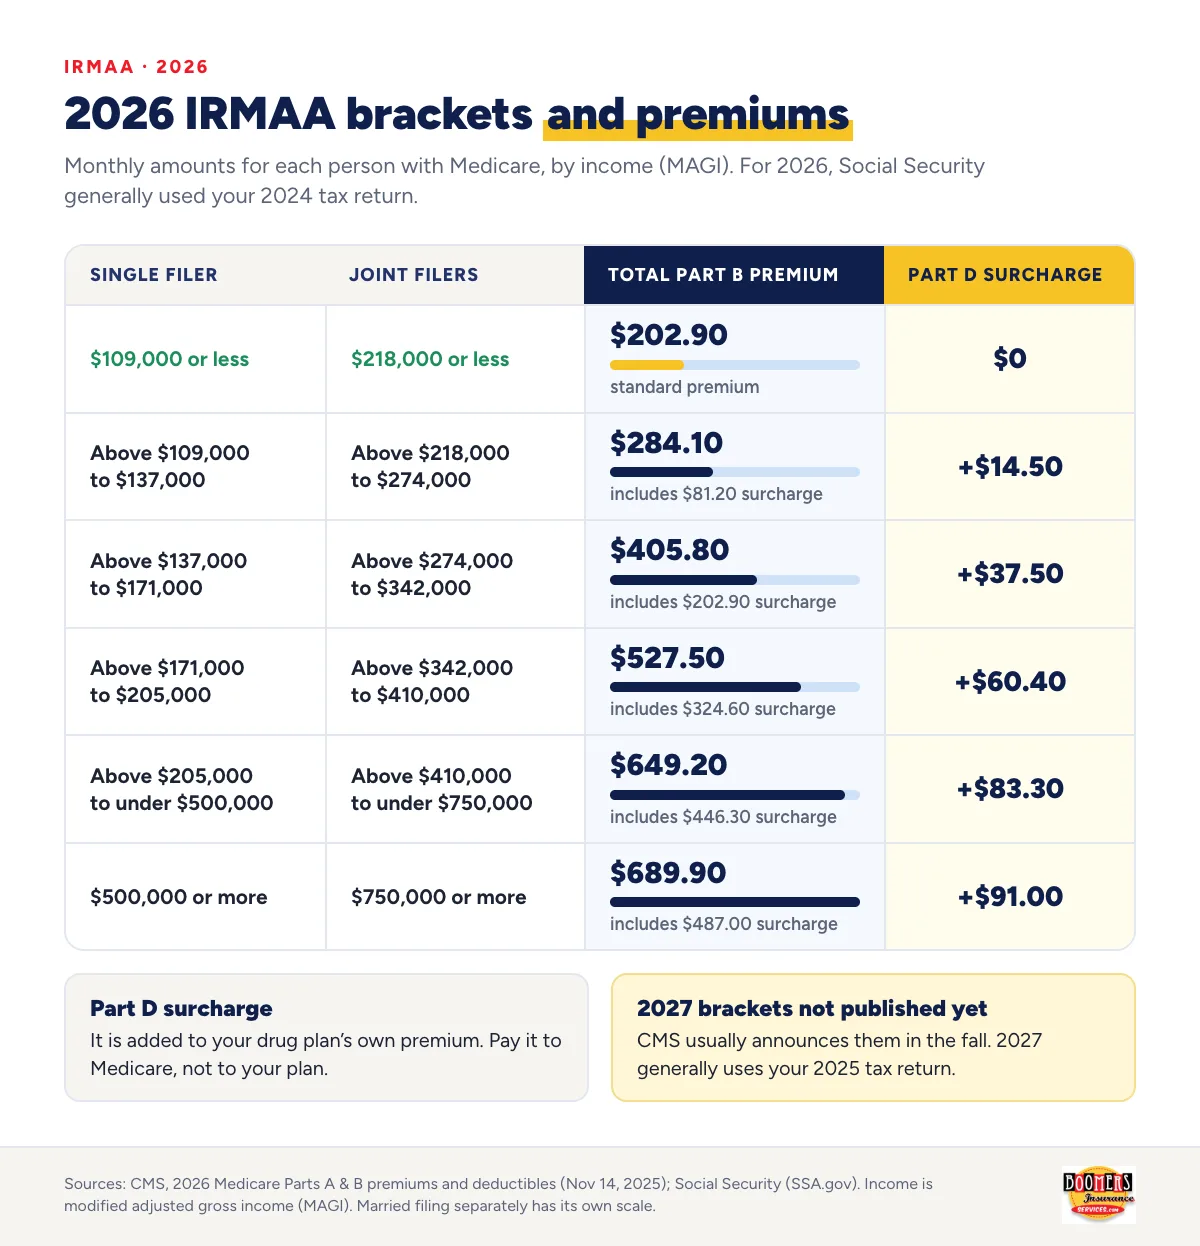
These are the IRMAA brackets 2026 from the CMS fact sheet (November 14, 2025) and Social Security. They apply to single filers and married couples filing jointly. The standard Part B premium in 2026 is $202.90 a month. The amounts are monthly, for each person with Medicare.
| Single filer MAGI | Joint filers MAGI | Part B surcharge | Total Part B premium | Part D surcharge |
|---|---|---|---|---|
| $109,000 or less | $218,000 or less | $0 | $202.90 | $0 |
| Above $109,000 to $137,000 | Above $218,000 to $274,000 | $81.20 | $284.10 | $14.50 |
| Above $137,000 to $171,000 | Above $274,000 to $342,000 | $202.90 | $405.80 | $37.50 |
| Above $171,000 to $205,000 | Above $342,000 to $410,000 | $324.60 | $527.50 | $60.40 |
| Above $205,000 to under $500,000 | Above $410,000 to under $750,000 | $446.30 | $649.20 | $83.30 |
| $500,000 or more | $750,000 or more | $487.00 | $689.90 | $91.00 |
The Part D surcharge is added to your drug plan's own premium. Social Security's Form SSA-44 says the single column also applies if you file as head of household or as a qualifying widow(er). It also applies if you are married filing separately but lived apart from your spouse all year.
2026 Medicare IRMAA thresholds if you are married and file separately
If you are married, lived with your spouse at any time during the tax year and file a separate return, a shorter scale applies:
| MAGI (married filing separately) | Part B surcharge | Total Part B premium | Part D surcharge |
|---|---|---|---|
| $109,000 or less | $0 | $202.90 | $0 |
| Above $109,000 and under $391,000 | $446.30 | $649.20 | $83.30 |
| $391,000 or more | $487.00 | $689.90 | $91.00 |
For 2026, Social Security generally used the tax return filed in 2025 for tax year 2024.
How much is the Medicare increase for 2026?
The standard Part B premium went from $185.00 in 2025 to $202.90 in 2026, an increase of $17.90 a month. The Part B deductible went from $257 to $283. The IRMAA surcharges are tied to the cost of Part B, so they move with it.
For the full picture of premiums, deductibles and the 2027 Part D figures, see our guide to Medicare cost in 2026 and 2027.
How is IRMAA billed?
Social Security decides your IRMAA and sends you a letter that explains it. The surcharge is not set by your plan.
- Part B: the surcharge is part of your Part B premium. It comes out of your Social Security payment. If it doesn't, Medicare usually bills you every three months, but you get a monthly bill if you also owe a Part D surcharge or pay a Part A premium.
- Part D: Social Security says it deducts the Part D surcharge from your monthly payment, no matter how you pay your plan's premium. If your payment is too small, or you don't get one, Medicare or the Railroad Retirement Board bills you.
- Medicare Advantage: if your plan includes drug coverage, Medicare & You 2027 says you pay the Part D surcharge too.
Pay the Part D surcharge to Medicare, not to your plan. Medicare & You 2027 warns that if you don't pay it, you could lose your drug coverage.
Can you lower IRMAA with Form SSA-44?
You may, if a life-changing event lowered your income. Form SSA-44 asks Social Security to use a more recent year's income instead of the old tax return. The events on the form are:
- Marriage
- Divorce or annulment
- Death of your spouse
- Work stoppage
- Work reduction
- Loss of income-producing property
- Loss of pension income
- An employer settlement payment
You need documents that show the event and the lower income, such as a letter from your employer about your retirement or a signed tax return. You can upload the form and your documents online after signing in to your Social Security account, mail or fax them, or bring them to a Social Security office. To ask for an interview, call Social Security at 1-800-772-1213 (TTY 1-800-325-0778).
A one-time gain, such as selling a house, is not on Social Security's list.
Other ways to correct an IRMAA decision
- You amended your tax return. Send Social Security a copy of the amended return and the IRS acknowledgment receipt.
- Social Security used an older return. If it used an older year but you filed a newer return, or didn't have to file one, call Social Security.
- The IRS figures are wrong. Social Security says you must correct them with the IRS.
- You disagree with the decision. You can appeal online or with a Request for Reconsideration (Form SSA-561-U2). You don't need an appeal if you are reporting a life-changing event.
Next steps
- Look at your 2025 tax return. The modified adjusted gross income on it will decide where you fall in the IRMAA brackets 2027.
- Watch for the CMS announcement this fall, and for any letter from Social Security about your 2027 premiums.
- If your income dropped because of an event on the SSA-44 list, gather your documents and contact Social Security.
- Review your plan choices for 2027 during Open Enrollment, October 15 to December 7. Our Annual Enrollment 2027 guide explains the dates.
Talk with a licensed Boomers agent
A licensed Boomers agent can go over the Medicare plans we represent in your area and check them against your doctors and prescriptions. We can't change your IRMAA, which Social Security decides, but we can show how it fits with each plan's own premium. Our help is at no cost to you.
Find a licensed agent near you · See upcoming Medicare events
Or call 1-800-815-1943 (TTY 711), Monday – Friday, 9 AM – 5 PM Pacific.
Frequently asked questions
When will the 2027 IRMAA brackets be announced?
CMS usually announces the next year's Part B premium and IRMAA amounts in the fall. The 2026 amounts were published on November 14, 2025. We will update this page when the 2027 figures are official.
What income is used for 2027 IRMAA?
Generally your 2025 tax return, filed in 2026. Social Security looks at your modified adjusted gross income: adjusted gross income plus tax-exempt interest. If the IRS doesn't have your 2025 return yet, Social Security may use 2024 and update it later.
What are the 2026 IRMAA thresholds?
In 2026 the surcharge starts above $109,000 of income for a single filer and above $218,000 for a joint return. The highest bracket starts at $500,000 (single) or $750,000 (joint). For married people who lived together but file separately, it starts above $109,000 and rises to the top amount at $391,000.
Do both spouses pay IRMAA?
The amounts in the CMS tables are per person. So if you file jointly and both of you have Medicare, each of you generally pays the surcharge for your joint income. If only one spouse has Medicare, the surcharge applies only to that spouse's premiums.
Is there an IRMAA for Part A?
No. IRMAA applies only to Part B and Part D premiums. Most people have Part A without a premium. If you buy Part A, its price depends on how long you or your spouse paid Medicare taxes, not on your income.
Sources
- 2026 Medicare Parts A & B premiums and deductibles (CMS.gov, November 14, 2025)
- Medicare premiums: rules for higher-income beneficiaries (SSA.gov)
- Form SSA-44, Medicare income-related monthly adjustment amount, life-changing event (SSA.gov)
- Lower your IRMAA (SSA.gov)
- Pay your Medicare premiums (Medicare.gov)
- Medicare & You 2027 (Medicare.gov)
- 42 U.S.C. 1395r(i), income-related reduction in Part B premium subsidy (GovInfo, U.S. Code)
Talk with a licensed Boomers agent
A licensed agent can go over the Medicare plans we represent in your area, check them against your doctors and prescriptions, and answer your questions. There is no cost to you and no obligation to enroll.
Monday – Friday, 9 AM – 5 PM PT